Gold Slid Despite the US-Iran Escalation, Rupee Opened 7 Paise Weaker at 95.88
Abstract:Gold and silver fell after the weekend's US-Iran escalation, and Indian markets opened lower on 28 September. The rupee opened 7 paise weaker at 95.88 against the dollar. Brent crude traded around $107 a barrel. US 10-year yields sat near 5.20%. Those figures come from trader posts on X, not from any media report in this material. None of them has been independently confirmed. Treat them as what traders saw on their screens at the open, not as settled fact. The counterintuitive part is the metals. War usually pushes gold up. This time it didn't. "Both precious metals had other plans after this weekend's US-Iran war escalation," wrote @YuvrajShah02, an account with 15,103 followers, roughly two hours after the open. The same post says Indian markets "have also taken a hit today." That post is the event this article is about. Everything below comes either from it or from other trader posts published the same morning.
Gold and silver fell after the weekend's US-Iran escalation, and Indian markets opened lower on 28 September. The rupee opened 7 paise weaker at 95.88 against the dollar. Brent crude traded around $107 a barrel. US 10-year yields sat near 5.20%.
Those figures come from trader posts on X, not from any media report in this material. None of them has been independently confirmed. Treat them as what traders saw on their screens at the open, not as settled fact.
The counterintuitive part is the metals. War usually pushes gold up. This time it didn't.
“Both precious metals had other plans after this weekend's US-Iran war escalation,” wrote @YuvrajShah02, an account with 15,103 followers, roughly two hours after the open. The same post says Indian markets “have also taken a hit today.”
That post is the event this article is about. Everything below comes either from it or from other trader posts published the same morning.
The Screen on 28 September
The numbers traders were passing around at the open:
- GIFT Nifty at 23,137, down 53.5 points
- Dow Jones up 0.93%, Nasdaq up 0.48%
- Rupee opening at 95.88 per dollar, 7 paise weaker
- Brent crude around $107 a barrel
- US 10-year yield near 5.20%
- Gold “sharply lower today”
The equity picture in India is not new. One post notes Indian equities were heading into the week after seven consecutive weekly declines. Another describes the momentum as still weak. A third calls the morning screen “mixed signals.”
So the split is this: US indices closed higher, Indian equities opened soft, and the rupee gave up ground. That combination is what a higher-oil, higher-yield morning looks like for an importer economy.
Why Gold Fell While a War was Escalating
The main post lays out a chain: sustained war, higher oil, higher inflation, higher chance of rate hikes, higher yields, higher dollar, lower gold.
Read it as one trader's model, not a forecast. But the links are worth understanding, because they run straight through the rupee.
India imports most of its crude. When Brent moves up, the import bill moves up in dollars. That widens the trade deficit and pressures the rupee. A weaker rupee makes those same barrels more expensive in rupee terms, which feeds into inflation. Higher inflation makes it harder for the RBI to cut rates, and can push it the other way.
US yields do the second half of the work. When the 10-year sits near 5.20%, dollar assets pay more. Money that would otherwise sit in emerging markets moves. Gold pays no yield at all, so it competes badly against a Treasury that pays 5.20%.
That is the mechanism the post describes. Whether it holds depends on whether the war is sustained. Nobody knows that yet, including the person who wrote the post.
What it Does to a USD/INR Position
If Brent stays near $107, the import bill stays elevated and the rupee keeps leaking. That is the direction of pressure, not a level.
For anyone holding USD/INR long, the mechanics cut two ways. A weaker rupee helps the spot position. But if the RBI leans against the move, forward premiums and swap points can shift, and the cost of carrying the position overnight changes with them. Higher US yields pull dollar funding costs up too, which shows up in the forward curve before it shows up in spot.
For anyone short USD/INR, the same logic runs in reverse. The spot move hurts, and the carry you were collecting can compress if the RBI tightens rupee liquidity to defend the currency.
Gold is the messier one. The post's own conclusion is that “entries only make sense when Gold and Silver stabilise.” That is a statement about timing, not direction. It also concedes the metals have not stabilised yet.
Where the Signals Disagree
The posts do not tell one clean story.
US equities closed higher. Indian equities opened lower. Gold fell while a war escalated. Those three things do not sit comfortably together, and no post in this material explains the gap.
The metals description is also vague. “Other plans” and “sharply lower” are not numbers. No post gives a gold or silver price, a percentage move, or a level.
There is no confirmation anywhere in this material of the scope of the escalation itself. No official statement, no casualty figure, no named government response. The phrase “US-Iran war escalation” appears in the main post and is repeated by others, but nothing here establishes what actually happened over the weekend.
And there is no media report in this material covering the same event. Every claim traces back to individual X accounts. That is the single biggest caveat on this entire article.
What Traders are Saying on X
Across the posts, three things repeat.
First, oil is the transmission channel. Brent near $107 appears in multiple posts, and one account lists crude, US bond yields and geopolitics as the three things Indian markets are entering the week focused on.
Second, volatility is expected to stay high. One post describes the outlook as cautious and says volatility is likely to remain elevated. Another flags that one number on the morning screen “needs attention” without saying which.
Third, the equity losing streak is the backdrop. Seven consecutive weekly declines is the figure that keeps coming up.
Where they diverge is on what it all means. The main post reads the chain as bearish for gold. Another account simply reports gold sharply lower and moves on. A third lists diesel and refined products as still under severe stress, which points at the inflation leg of the chain rather than the metals leg.
None of these accounts is a primary source. Follower counts range from about 1,300 to 18,700. Engagement on the main post was 73 likes, 1 repost and 8 comments. That is a small sample of opinion, not a market consensus.
What to Watch Next
There is no confirmed data release or central bank meeting date anywhere in this material. The main poster says only that he will keep posting updates through the week.
So the practical checklist is the screen itself. Watch Brent around $107. Watch where USD/INR opens relative to 95.88. Watch the US 10-year around 5.20%. Watch GIFT Nifty around 23,137. Those four numbers are the inputs in the chain the post describes, and each one is observable in real time.
If Brent pushes further above $107, the inflation and yield legs of that chain get stronger, and the carry cost on a long USD/INR position becomes the thing to check before the spot move. If Brent retreats, the whole chain weakens at its first link.
For scheduled events, the RBI publishes its monetary policy dates on rbi.org.in, and the Ministry of Statistics releases inflation and trade data on mospi.gov.in. Neither calendar is reproduced here because this material does not contain those dates.
One more thing worth doing: check whether the escalation itself has been confirmed by a wire service or a government statement before acting on any of the above. As of this writing, it has not been, in this material.
Download the WikiFX app for the latest financial news and updates.
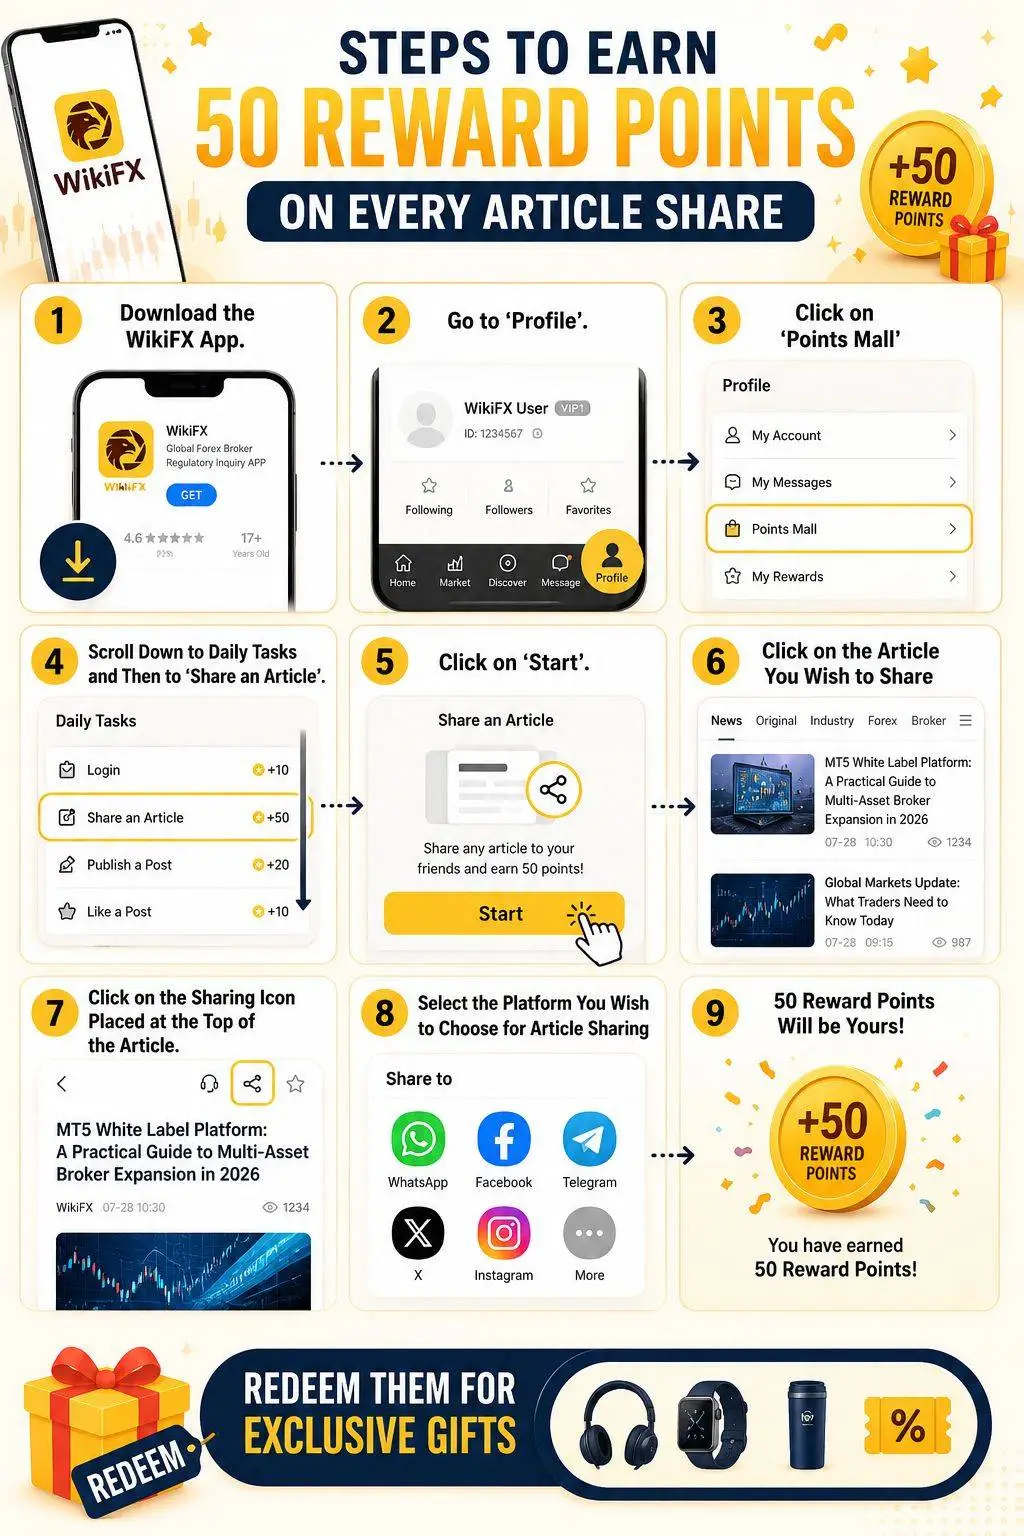
Knowledge pays at WikiFX.Every time you share a WikiFX article, you'll receive 50 Reward Points. Grow your rewards with every share and unlock exclusive gifts in the WikiFX Points Mall. Start earning today!
Read more
Deriv Review 2026: Reported Manipulative Trading Charts, Withdrawal Denial & Deposit Failure
Deriv, a Malta-based brokerage firm, receives multiple allegations on trading charts that are allegedly not in traders' interest. The constant price spikes on the Deriv platform usually lead to losses for traders, according to the user reviews shared on broker evaluation platforms such as WikiFX. Additionally, users have reported withdrawal issues and deposit credit failures on the trading platform. In this Deriv review 2026, we have examined multiple user allegations and shared its regulatory framework.
InstaForex Review of a USD 600 Deposit Complaint with Entity Limits
This InstaForex review revisits a Malaysian user's complaint dated 8 October 2021 about a USD 600 deposit, a matching bonus, and a rejected withdrawal. It is a historical case study for India and South Asia readers, not a new local incident. The website was checked on 28 September 2026. The central issue is how to distinguish account credit, withdrawable funds, and the company responsible for the account.
Savexa Review 2026: Examining Trade Allegations of Indian Users
Savexa, a Comoros-based brokerage firm, reportedly received mixed reviews from users across India. While some hailed its competitive spread and trade order execution capability, others report fake profit and constant deposit pressure. The negative Savexa reviews reportedly had more insights and depth, which called for an investigation. In this article, we have examined these reviews thoroughly and disclosed whether Savexa is regulated.
SEBI's New PMS Rules Let Fund Managers Run 'Sub-PMSes' — But the Fine Print is Still Open
SEBI's board on September 24 approved a sweeping overhaul of portfolio management rules, opening PMS to foreign securities, IPOs and a new mutual-fund-only route called PRIM. But one X user with 101,000 followers flagged a structural change that could reshape how PMS products are sold: a 'platform PMS' can now host independent fund managers (IFMs), each running their own strategy on the PMS's licence. Under the new SEBI (Portfolio Managers) Regulations, 2026, replacing the 2020 framework, existing PMS can invest in foreign securities under both discretionary and non-discretionary mandates, according to multiple media reports. The allowed list includes listed equity, debt, REITs, overseas mutual funds, ETFs, index funds and foreign government debt. All of it stays bound by FEMA and RBI's Liberalized Remittance Scheme — so you still can't buy foreign ETFs in rupees. The PMS just becomes a wrapper.
WikiFX Broker
Latest News
Romance and Investment Scams Drain Billions From Asia
WikiFXTopstep Review: Is This Prop Trading Firm Safe & Trustworthy?
WikiFXFed Interest Rate Forecast: PCE Report Nears as 10-Year Yield Remains Above 5%
WikiFXInstaForex Review of a USD 600 Deposit Complaint with Entity Limits
WikiFXTriumphFX Broker Exposed: Withdrawal Complaints and Regulatory Warnings
WikiFXPRICE IS KING — BUT WHY IGNORE THE TOOLS THAT HELP YOU READ IT
WikiFXGold Slid Despite the US-Iran Escalation, Rupee Opened 7 Paise Weaker at 95.88
WikiFXDeriv Review 2026: Reported Manipulative Trading Charts, Withdrawal Denial & Deposit Failure
WikiFXRate Calc
