Elevated Stocks and High Rates: October Rate Decision Takes Center Stage
Abstract:[Figure 1: Inflation-Adjusted SP 500 Index | Source: Multpl]High Stock Valuations and High Interest Rates Leave Markets Increasingly SensitiveThe 10-year U.S. Treasury yield has moved higher again, cu
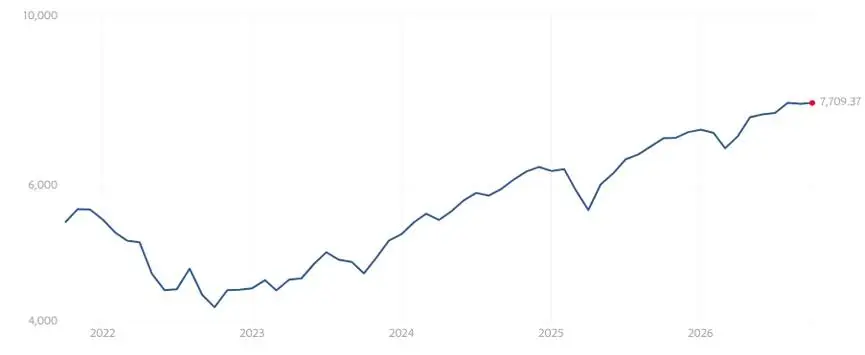
[Figure 1: Inflation-Adjusted S&P 500 Index | Source: Multpl]High Stock Valuations and High Interest Rates Leave Markets Increasingly Sensitive
The 10-year U.S. Treasury yield has moved higher again, currently hovering around 5.2%–5.3%, near its highest levels in roughly two decades. At the same time, the inflation-adjusted S&P 500 remains close to a record high at around 7,709. This combination of elevated equity valuations and high interest rates has left markets increasingly sensitive to shifts in the macroeconomic outlook.
As Figure 1 illustrates, periods of rapidly rising interest rates tend to exert immediate pressure on equities, with 2022 serving as a clear example. However, once markets adjust to a higher-rate environment, continued growth in corporate earnings can still drive stocks to new highs, as demonstrated by market performance from 2023 through 2025.
The market is now in an unusual environment where both real equity prices and the 10-year Treasury yield remain at relatively elevated levels. Going forward, investors should closely monitor the path of real interest rates, the persistence of inflation, and the Federal Reserves policy trajectory.
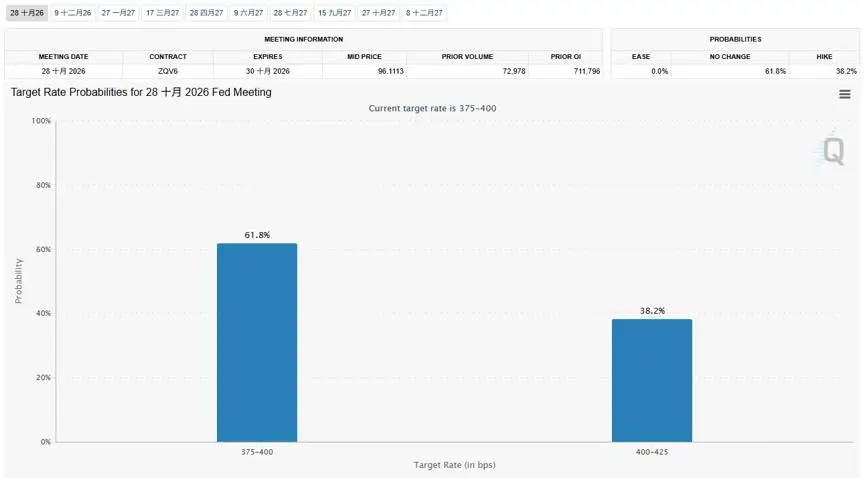
[Figure 2: Probability of a Federal Reserve Rate Hike by Year-End | Source: CME]Lower Odds of an October Rate Hike Could Ease Market Pressure
As shown in Figure 2, the latest data indicate a 61.8% probability that the Federal Reserve will keep interest rates unchanged, compared with a 38.2% probability of a 25-basis-point rate hike.
This probability distribution suggests that markets are still weighing persistent inflation pressures against the outlook for economic growth. While expectations for another rate hike are not the dominant scenario, the possibility remains significant enough to influence market pricing.
If the Fed ultimately leaves rates unchanged, it could help ease the valuation pressure created by the recent rise in Treasury yields and provide a relatively stable backdrop for equities near record highs.
If policymakers instead opt for another rate hike, long-term Treasury yields could move even higher, intensifying the tension between elevated interest rates and high equity valuations. Such an outcome could increase the likelihood of greater short-term volatility in inflation-adjusted equity prices.
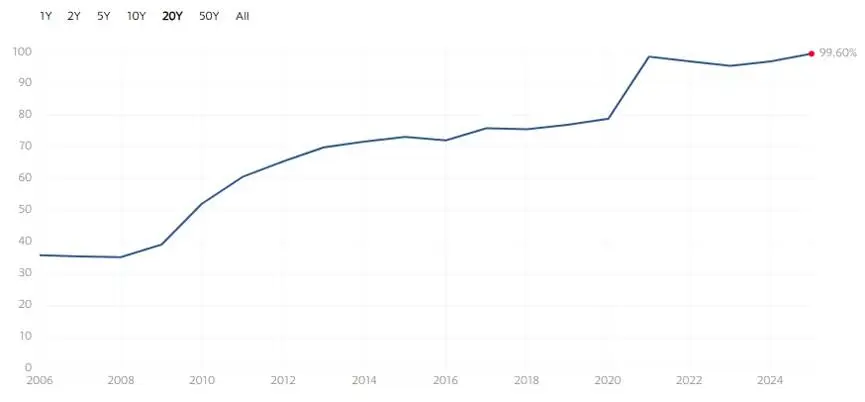
[Figure 3: U.S. Federal Debt as a Percentage of GDP | Source: Multpl]U.S. Debt Remains Elevated, Making Interest Rates a Critical Factor
Figure 3 shows that U.S. federal debt currently stands at approximately 99.60% of GDP, reflecting a long-term upward trend that contrasts sharply with todays high-interest-rate environment.
A heavier debt burden means that government interest expenses place greater pressure on public finances. With the 10-year U.S. Treasury yield hovering around 5.2%–5.3%, borrowing costs are substantially higher than during the low-rate environment that prevailed for much of the past decade.
As a result, markets have become increasingly sensitive to expectations surrounding Federal Reserve policy. If interest rates remain elevated or rise further, concerns over debt sustainability could intensify. Conversely, a shift toward monetary easing could help reduce pressure from rising interest costs.
From a market perspective, a high debt-to-GDP ratio does not directly determine the direction of equity prices. Instead, it affects valuations and risk appetite indirectly through its interaction with interest rates and fiscal policy.
Historical experience suggests that periods of elevated government debt can coincide with a higher long-term interest-rate environment. This provides part of the broader macroeconomic backdrop behind the current combination of relatively high inflation-adjusted equity prices and elevated Treasury yields.
Risk Disclosure: The views, analysis, research, prices, and other information provided above are for general market commentary purposes only and do not represent the official position of this platform. Readers should independently assess all relevant risks and exercise caution when making trading or investment decisions.

WikiFX Broker
Latest News
Alpari Broker Exposed: What Are Other Traders Saying About This Broker?
 WikiFX
U.S. Dollar Tests New Highs As 30-Year Yield Hits 5.60%: Analysis For EUR/USD, GBP/USD, USD/CAD, USD/JPY
WikiFXWeltrade Review 2026: Chart Error, Withdrawal Cancellation and Unaccounted Fund Deduction Claims
WikiFXGOAT FUNDED TRADER Review: Is This Prop Trading Firm Safe & Trustworthy?
WikiFXUS Dollar Price Forecast: Dollar Holds Firm as Fed Bets Ease, EUR/USD and GBP/USD Struggle
WikiFXUK Opens Crypto Gateway Ahead of Regulatory Overhaul
WikiFXMarketsall Review of a May 2025 Withdrawal Complaint and Unresolved Questions
WikiFXTrade W Broker Exposed: User Feedback, Delayed Orders and Office Survey
WikiFXBrent Clears $108 and ₹17 Lakh Crore Exits Indian Stocks — PSU Banks Took the Worst Hit
WikiFXCash FX Accused of $950 Million Forex Fraud
WikiFXRate Calc
