Adani's SEBI Mart: Five Group Firms Pay ₹15 Crore to Settle Disclosure Violations
Abstract:Five Adani Group companies, including the flagship Adani Enterprises, have paid a total of ₹15.1 crore to settle a disclosure violation case with India's market regulator, SEBI. The settlement, confirmed by multiple media reports on Tuesday, closes the enforcement proceedings that stemmed from the Hindenburg Research report of January 2024. The social media post that flagged this development was blunt: "Welcome to Adani's SEBI Mart." The post, shared by comparison even fair? Let's dig into the numbers and the fine print.
Five Adani Group companies, including the flagship Adani Enterprises, have paid a total of ₹15.1 crore to settle a disclosure violation case with India's market regulator, SEBI. The settlement, confirmed by multiple media reports on Tuesday, closes the enforcement proceedings that stemmed from the Hindenburg Research report of January 2024. The social media post that flagged this development was blunt: “Welcome to Adani's SEBI Mart.”
The post, shared by comparison even fair? Let's dig into the numbers and the fine print.
The Settlement: What Exactly Was Paid and Who Paid It?
The settlement order, issued by SEBI on September 22, covers five Adani entities: Adani Enterprises, Adani Green Energy, Adani Power, Adani Total Gas, and Adani Transmission (now known as Adani Energy Solutions). and Adani Transmission ₹2.0 crore. A sixth entity, Adani Ports, was also named in the original proceedings but settled separately earlier this year.
The charges relate to alleged violations of Listing Obligations and Disclosure Requirements (LODR) regulations — specifically, the failure to disclose certain transactions and related-party dealings that Hindenburg had highlighted. The settlement is not an admission of guilt. In fact, the standard SEBI settlement order includes a “no admission, no denial” clause, meaning the companies neither admit nor deny the allegations. They just pay the fee and move on.
The Social Media Backlash: 'SEBI Mart' and the Perception Problem
The X post that triggered this article has 68 likes and 42 retweets — modest numbers, but the sentiment it captures is widespread among Indian retail investors. The post's author, @FightAnand, uses a thread format (“1/n”) to walk through the timeline: from Hindenburg's allegations, to Adani's fiery denials, to this quiet settlement. The phrase “SEBI Mart” is a play on the Adani-owned supermarket chain, becoming implying that regulatory has enforcement a marketplace where violations have a price tag.
This is not an isolated view. A quick scan of replies and quote-tweets on similar posts shows a recurring theme: investors feel that the settlement mechanism, while legally valid, creates a two-tier system. If you're a small company, you get a show-cause notice and a lengthy investigation. If you're a conglomerate with deep pockets, you pay a fine that's a rounding error on your balance sheet. Whether that perception matches reality is debatable, but it's a powerful narrative that's hard to shake.
The Hindenburg Context: From 'Attack on India' to a Quiet Settlement
To understand why this settlement stings, you need to recall the original clash. In January 2024, Hindenburg Research published a scathing report accusing the Adani Group of “brazen stock manipulation and accounting fraud” — allegations the group has consistently denied. The report's release triggered a $100 billion+ selloff in Adani stocks, wiping out nearly half the group's market value in a week. At the time, Adani's top brass called it “an attack on India” and “a big lie,” and threatened legal action against Hindenburg.
Fast forward 20 months, and the resolution is a settlement order that runs to 47 pages. The irony is not lost on market watchers. The original Hindenburg report made specific allegations about offshore shell companies and undisclosed related-party transactions. The SEBI investigation, which was ordered by the Supreme Court, focused narrowly on whether Adani companies violated LODR disclosure norms — not on the broader fraud allegations. That's a crucial distinction. The settlement covers only the disclosure lapses, not the underlying claims of stock manipulation.
How the Settlement Mechanism Works: Money for Nothing?
SEBI's settlement mechanism, governed by the SEBI (Settlement of Proceedings) Regulations, 2018, allows entities to resolve enforcement actions without admitting or denying guilt. The process is voluntary — the company applies, pays a fee, and the regulator closes the case.
Critics argue that the mechanism is fundamentally flawed. For a company with a market cap of ₹10 lakh crore, a ₹15 crore fine is 0.0015% of its value — a parking ticket, not a penalty. Moreover, the “no admission, no denial” clause means the company can continue to deny wrongdoing, which makes it harder for investors to sue for damages in civil court. The settlement also doesn't bar future enforcement actions for the same conduct, though in practice, SEBI rarely revisits settled cases.
Divergences and Unanswered Questions
Not all reports agree on the details. Reuters, which first reported the settlement, noted that the order was passed on September 22 and that the companies “have paid a total of 15.1 crore.” However, the Economic Times report lists the same figure but adds that the settlement is “without prejudice to the rights of SEBI to initiate proceedings for any other violations.” The Bar and Bench report, meanwhile, highlights that the settlement covers “disclosure violations” specifically, and that the order “does not comment on the underlying merits of the allegations.”
There's also a discrepancy in the number of companies. The X post says “5 Adani group companies” settled, which matches the SEBI order. But the original Hindenburg report named six Adani entities. The sixth, Adani Ports, settled separately in an earlier proceeding. So the count is correct, but the optics are muddled. “manipulative scheme.”
What Should Retail Investors Do Now? A Checklist for Spotting Similar Red Flags
If you're an Indian retail investor, the Adani settlement is a reminder that regulatory enforcement has limits. But it's also a case study in how to read between the lines. Here's what to watch for in any similar situation:
- The 'No Admission, No Denial' Clause : If a company settles a regulator case without admitting wrongdoing, treat it as a red flag. It's a legal maneuver that protects the company, not you.
- The Settlement Amount vs. Market Cap Ratio : Calculate the fine as a percentage of the company's market cap. If it's less than 0.1%, the penalty is likely a cost of doing business, not a deterrent.
- The Timing : Note how long it took from the original allegation to the settlement. A quick settlement (under a year) suggests the company wanted to move on. A delayed one (over two years) might indicate a more complex issue.
- The Scope of the Settlement : Read the order carefully. Does it cover all the allegations, or just a narrow set of technical violations? In this case, SEBI only looked at disclosure lapses, not the broader fraud claims.
- The Company's Response : Did the company call it a “vindication”? That's a tell. Settling is not vindication — it's a business decision. If the company's statement uses aggressive language, it's likely trying to manage the narrative.
- Check the SEBI Website : All settlement orders are public. Search for the company name in the “Settlement Orders” section of sebi.gov.in. You can also check the “Enforcement Orders” tab for any ongoing proceedings.
- The 'One-Off' Trap : Ask yourself: is this the first time the company has settled with a regulator, or is it a repeat offender? A history of settlements is a bigger red flag than a single incident.
The Bottom Line: A Fine, Not a Verdict
The Adani settlement is a legal fact, but its interpretation is up for grabs. For the company, it's a closed chapter. For SEBI, it's a routine enforcement action. For retail investors, it's a reminder that “settlement” is not the same as “justice.”
If you hold Adani stocks, the settlement doesn't change your position — the shares have already recovered most of their post-Hindenburg losses. But if you're looking for a signal about how SEBI handles big corporate cases, this is it. The regulator has the legal framework to impose real penalties, but it chose to settle. Whether that's pragmatism or leniency is a question only time — and future cases — will answer.
For now, the next date to watch is the Supreme Court's hearing on the PILs related to the Hindenburg report, which is scheduled for later this year. That's where the broader questions about market manipulation and regulatory oversight will be tested. Until then, the settlement stands — and the debate over “SEBI Mart” will continue ---
Download the WikiFX app for the latest financial updates.
Knowledge pays at WikiFX.
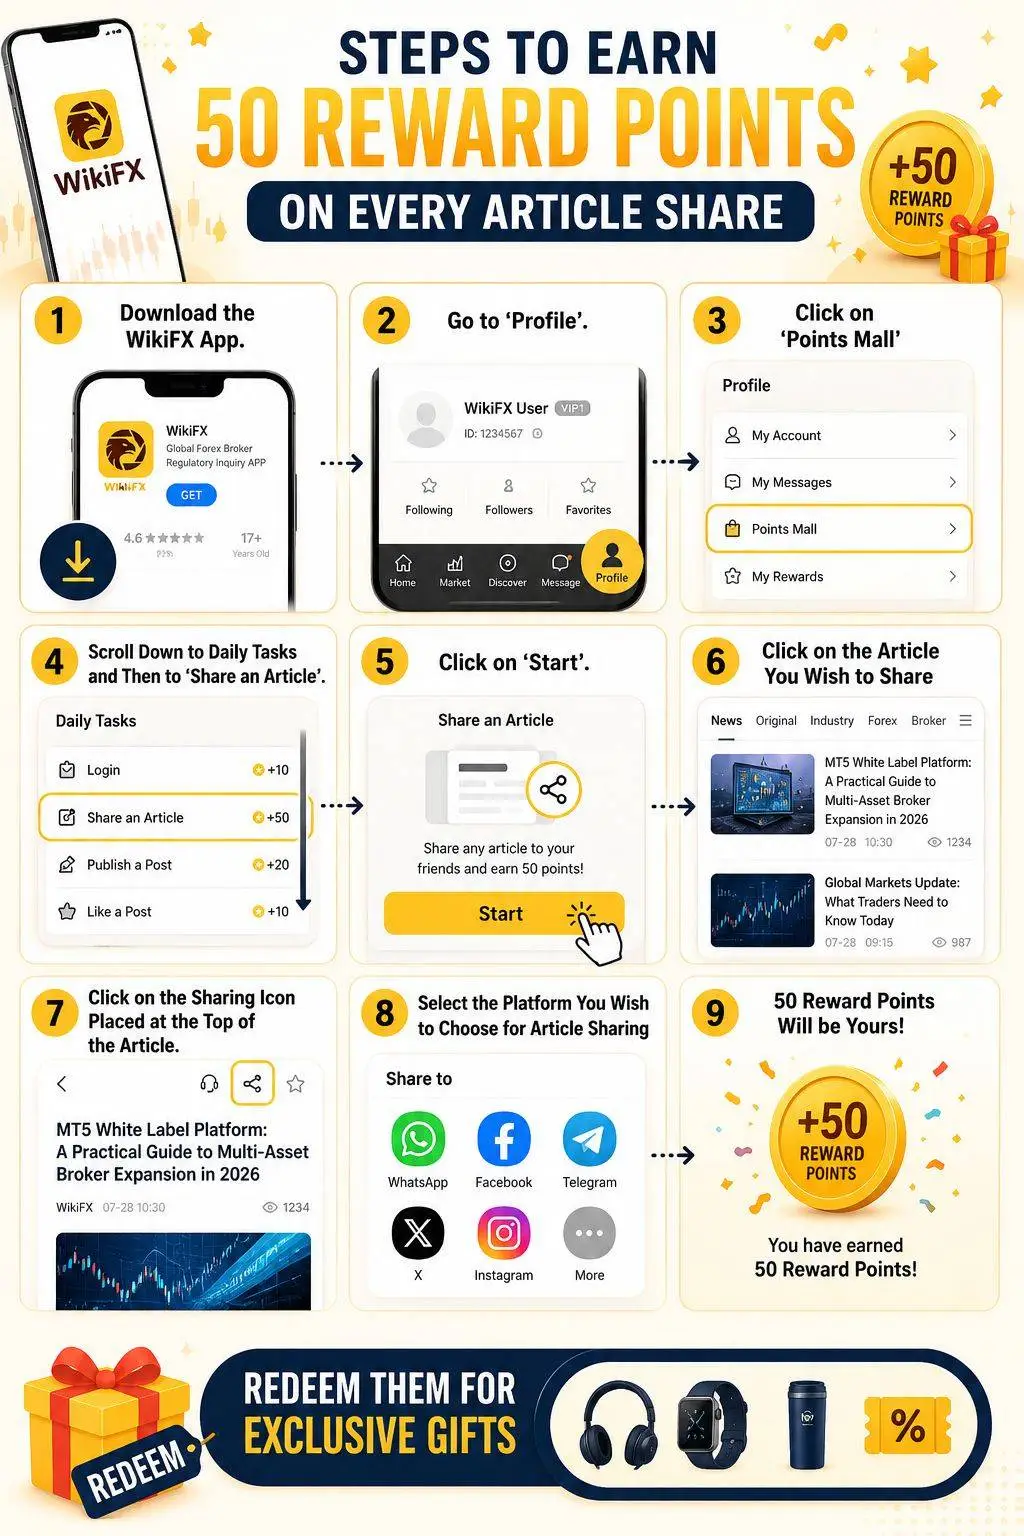
Every time you share a WikiFX article, you'll receive 50 Reward Points. Grow your rewards with every share and unlock exclusive gifts in the WikiFX Points Mall. Start earning today!
Read more
FII Exodus: Rupee Depreciation, 5% US yields — Why Foreign Capital Keeps Leaving India
FIIs have been selling Indian equities for six years, and a viral post says the reason is simple: the rupee keeps falling, US yields pay 5%, so why would foreign money stay? Read on more updates.
Uday Kotak Warns India's Gold Import Bill is Heading for $90 Billion
Gross gold imports could reach $88-90 billion in FY27, the Kotak Mahindra Bank founder told a conference in New Delhi on Friday, and he wants a committee created to work out how India pays that bill without damaging its external accounts. The same speech carried a second number. Kotak expects the current account deficit to widen to roughly $60 billion in FY27 if crude averages about $90 a barrel. Gold does most of that damage. Strip gold out, and India ran a current account surplus in FY26. He was speaking at the Conference on Financing India's Journey Towards Viksit Bharat, a gathering on capital formation. ANI carried the remarks, and a string of outlets across business media reproduced them over the weekend. "India needs to find a way to balance household demand for gold with the impact of imports on the country's external finances," Kotak said, according to Analytics Insight. He suggested the government consider setting up a committee to examine the issue. He also flagged the
NSE Cuts Its IPO Valuation by 15% — and the Unlisted Market Is Still Pricier
NSE has cut the valuation of its initial public offering by roughly 15% and shrunk the deal to about ₹22,500–23,500 crore, down from an earlier plan of nearly ₹30,000 crore. The offer is entirely an offer for sale. Not a rupee of the proceeds goes to the exchange itself. The revised plan puts 12.64 crore shares on the block, against the 14.89 crore proposed earlier. That works out to about 5.25% of NSE's paid-up capital, down from nearly 6%. Two numbers moved. The float got smaller and the price got lower. Everything else in the revision follows from those two.
India Just Bought a Record $15.2B of US Treasures in July — What It Means for INR and FII Flows
India bought a record $15.2 billion of US Treasures in July, lifting its total holdings to $202.6 billion from $186.4 billion in June, according to US Treasury data. The jump is the largest monthly net purchase on record for India, and it comes as China's holdings slid to an 18-year low. The figure was flagged by market commentator @Equities_Fraise on X, who noted the buying usually signals strong overseas capital inflows and RBI facilities pulling money in. The post, which has just 8 likes, points to better forex comfort and global confidence in India flows. The data itself is from the US Treasury's TIC report, released September 16.
WikiFX Broker
Latest News
U.S. Dollar Rallies As 10-Year Treasury Yield Tests New Highs: Analysis For EUR/USD, GBP/USD, USD/CAD, USD/JPY
WikiFXRM330,000 Invested, Only RM35,000 Comes Back
WikiFXSTARTRADER Opens Weekend Trading on Two Chinese AI Stocks
WikiFXAzure Markets Review After Its Licence Page Returned 404
WikiFXUSD and Commodities Forecasts: Some Maps Changed, Others Just Paid Off
WikiFXWikiFX Wishes You a Happy Mid-Autumn Festival
WikiFXJustMarkets Review 2026: Withdrawal Delay & Trade Execution Error Complaints Surface
WikiFXMeta Dismantles 3.8 Million Scam Linked Pages
WikiFXFUNDEDNEXT Review: Is This Prop Trading Firm Safe & Trustworthy?
WikiFXINZO Review 2026: Withdrawal Denial, Bonus Failure & Poor Customer Support Allegations
WikiFXRate Calc
