What Is a Hybrid Market?
Abstract:A hybrid market is an exchange where traders may conduct deals using both automated trading tools and conventional floor brokers. The New York Stock Exchange is the most well-known example of a hybrid market in the United States (NYSE).
Market participants in hybrid markets can select between fully automated electronic exchange systems and human floor brokers who execute deals on the actual trading floor. Despite the fact that both techniques have merits and limitations, there has been a recent trend toward completely computerized order fulfillment.
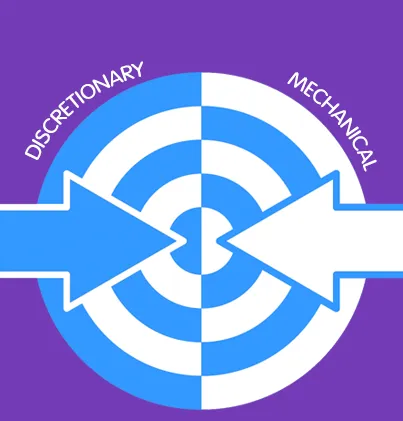
The advantage of hiring floor brokers is that they may use human judgment in the way and time in which they enter deals, despite the fact that they are slower and more expensive than entirely computerized systems. In general, they are only used by large institutional clients and a select few high-net-worth individuals. In order to make deals that are delicate in nature, these customers may need to rely on the human judgment and experience of a floor broker.
Investors placing big orders, for example, may wish to keep their order from becoming public information so that other investors do not attempt to front-run the transaction. Floor brokers could be able to help with such a deal by scouring their network of institutional customers for possible counterparties.
Clients may also rely on floor brokers' skills to spread out their trade executions across time in order to avoid impacting the price of the securities while the deal is being completed. For example, if an investor desires to acquire a large number of shares in a sparsely traded firm, putting the full purchase through a single order may cause the price to rise before all of the shares can be purchased, raising the transaction's overall cost. A floor broker may be trusted to keep a close eye on this transaction and issue buy orders progressively to keep the overall cost low.
Floor brokers, on the other hand, are generally unnecessary or impractical for retail investors. These investors will seldom be worried about impacting the market price of the assets they acquire because of their minimal transaction amounts.
A Hybrid Market in the Real World
For the majority of its existence, the NYSE, one of the world's oldest and most prestigious stock exchanges, relied on human trade brokers on its physical trading floor. The NYSE, on the other hand, made practically all of its listed equities available for electronic trading in January 2007. 1
Although these equities can still be traded on the trading floor by brokers, consumers can now choose for electronic executions. In practice, today's market participants place the great majority of transactions electronically, with human brokers mostly representing huge institutional customers. Many exchanges throughout the world have now completely abolished their physical trading floors, claiming the greater efficiency of electronic trading as the reason.

Read more
FBS Review 2026: Are Withdrawal Delays and Trading Errors Frustrating Users?
FBS, a Belize-based brokerage firm, is a recognized name in the trading community, courtesy of its wide-ranging product portfolio. With a minimum deposit of $5 and a leverage of up to 1:3000, it grabs users' attention. But does all of that translate into a seamless experience for users? For some, the platform reportedly has not yielded good outcomes. They have accused the broker of withdrawal delays and trade manipulation. This FBS review 2026 examines several user-reported allegations and reveals its regulatory framework.
eToro Review 2026: Traders Allege Platform Errors Behind Unexpected Losses
Are you an eToro trader who has been made to pay fees yet is facing slippage on your trades? Did you lose trades because of the unexpected closure of open positions? Did your trade fail to execute because of systemic bugs? These negative eToro reviews pointing to potential platform glitches have reportedly become synonymous with most traders worldwide. Some of these reviews appeared on broker evaluation platforms such as WikiFX. In this article, we have thoroughly investigated user allegations and provided an overview of its regulatory framework.
India's Retail Inflation Hits 6.1%, Breaching RBI's Ceiling for First Time in Two Years
India's retail inflation rose to 6.1% in October 2026, crossing the Reserve Bank of India's upper tolerance limit for the first time in two years, according to data released by the government and reported by The Hindu. The reading puts price growth above the 6% ceiling of the central bank's 2% to 6% comfort band, a zone it last breached in October 2024, when inflation stood at 6.2%.
Fed Note Says Gold Repatriation Is Not Automatically a Dollar Exit
Headlines about central banks flying their gold home are often read as a verdict on the U.S. dollar. A Federal Reserve research note published on November 9 argues that reading is too simple: for the euro area central banks that moved gold out of U.S. custody, the dollar's share of their reserves barely moved. According to the Federal Reserve, the note reviews relocations by Germany, the Netherlands and France since 2013 and the changes, or lack of them, in their U.S. dollar reserve allocations.
WikiFX Broker
Latest News
What I Am Watching Today: EUR/USD, USD/CHF, GBP/USD, and Copper
 WikiFX
RoboForex Review: Is Your Deposit Safe?
WikiFXRupee Breaks Past 93.60 as Nearly $10 Billion in Foreign Equity Inflows Return
WikiFXMAS to Start 2027 Study on Industry-Wide Scam Detection Utility Built on Five-Bank AI Trial
WikiFXAUD and GBP Fall as Fed Rate Bets Shift, Bitcoin Tests $62K Amid Double-Hike Expectations
WikiFXFour roles between your deposit and your forex price
WikiFXBEARISH MARKET OUTLOOK | DOWNSIDE CONTINUATION
WikiFXUSD/JPY Retreats from 160 on Risk Aversion, While Bitcoin Falls to $61.8K Amid Stock Selloff
WikiFXRoboForex Review 2026: Should Traders be Concerned About Withdrawal Complaints?
WikiFXUnemployment Jumps to 4.9pc, Highest Since 2021, as Economists Tip RBA to Hold
WikiFXRate Calc
