NSE Cuts Its IPO Valuation by 15% — and the Unlisted Market Is Still Pricier
Abstract:NSE has cut the valuation of its initial public offering by roughly 15% and shrunk the deal to about ₹22,500–23,500 crore, down from an earlier plan of nearly ₹30,000 crore. The offer is entirely an offer for sale. Not a rupee of the proceeds goes to the exchange itself. The revised plan puts 12.64 crore shares on the block, against the 14.89 crore proposed earlier. That works out to about 5.25% of NSE's paid-up capital, down from nearly 6%. Two numbers moved. The float got smaller and the price got lower. Everything else in the revision follows from those two.
NSE has cut the valuation of its initial public offering by roughly 15% and shrunk the deal to about ₹22,500–23,500 crore, down from an earlier plan of nearly ₹30,000 crore. The offer is entirely an offer for sale. Not a rupee of the proceeds goes to the exchange itself.
The revised plan puts 12.64 crore shares on the block, against the 14.89 crore proposed earlier. That works out to about 5.25% of NSE's paid-up capital, down from nearly 6%.
Two numbers moved. The float got smaller and the price got lower. Everything else in the revision follows from those two.
What Changed: Fewer Shares, Lower Price, Smaller Stake
The earlier plan was for an offer of up to 14.89 crore shares. The revised plan cuts that to around 12.64 crore. The total issue size falls from nearly ₹30,000 crore to ₹22,500–23,500 crore.
Public reports put the final figure at ₹22,561.57 crore. Groww, Upstox and Jagran Josh all use that number, and Upstox confirms the offer is an OFS of up to 12.64 crore shares.
The stake on offer drops from nearly 6% of paid-up capital to roughly 5.25%. That is a small change in percentage terms and a large one in rupees — the difference between the old and new plans is somewhere around ₹7,000 crore of stock that will not be sold.
Pricing is the other half. NSE shares have traded between ₹1,900 and ₹2,050 in the unlisted market over the past year. The IPO price is expected to come in below those levels. At a valuation of roughly 43 times FY26 earnings, the exchange would still carry a significant valuation — though comparisons with listed market-infrastructure peers such as BSE and MCX are part of how investors will judge it.
An all-OFS Deal Means NSE Gets Nothing
This is the part retail investors most often miss. A fresh issue raises money for the company. An offer for sale does not. NSE's IPO is entirely the second kind.
Existing shareholders sell part of their holdings to public investors. The exchange's balance sheet does not change. The cash goes to the selling shareholders.
One of them is Soach Global. The fund will sell 20% of its decade-old stake in the IPO and hold the remaining 80% as a long-term investment, according to TheWire.in, which carried the PTI release. The same report says the fund is set for nearly 25x gains on that partial exit.
That is the arithmetic of an OFS in one line: the company gets a listing, the selling shareholder gets the money. If you are buying the IPO, you are buying from an existing holder, not funding the exchange's next project.
The Unlisted Market Was Already Pricing NSE Higher
NSE shares have changed hands in the unlisted market at ₹1,900–₹2,050 over the past year. The revised IPO price is expected to sit below that range.
That gap is the reason the valuation cut drew attention. Investors who bought in the unlisted market at those levels are looking at an IPO that prices lower than what they paid.
The main post frames the revision as a balancing act: a very high valuation could hurt demand, while a lower one gives more comfort to investors entering through the IPO. Both statements describe the same trade-off — how much of the upside goes to the seller and how much is left for the buyer.
Derivatives Pay the Bills, and SEBI Writes the Rules
Around 60% of NSE's operating revenue comes from derivatives. That is the single most important number for anyone trying to value the exchange.
It is also the number most exposed to regulation. SEBI rules on retail participation, expiry structures, transaction charges and trading activity can all move derivatives volumes, and therefore NSE's revenue.
The main post flags this directly: the segment is an important source of earnings, and it is subject to regulatory and volume-related changes. Nothing in the material says a specific rule change is pending. The exposure is structural, not event-driven.
Where the Reported Numbers Disagree
The issue ran from September 17 to September 21, 2026, and closed on its third and final day of bidding. Reports on the final day do not agree on how much demand came in.
HDFC Sky recorded the issue at 1.46x on September 21, with retail at 0.88x, non-institutional at 2.32x and QIB at 1.83x. Upstox put it at 2.56x “so far” on the same day. Moneycontrol said the issue was subscribed over 2x with the retail portion fully subscribed. Rediff MoneyWiz reported nearly 4x on the final day and called it India's second-largest public issue.
These are snapshots taken at different points during a single day of bidding, which explains part of the spread. The retail line is the one that flips outright: HDFC Sky has retail below full subscription at 0.88x, while Moneycontrol describes the retail portion as fully subscribed.
On the gray market, The Times of India and Moneycontrol both put the premium at 3% on Day 3. Moneycontrol notes it declined to that level.
What Traders are Saying on X
The post that started this — from @itspixora, an account with 6,135 followers — asks why the issue is priced below unlisted-market levels and lays out the valuation cut, the OFS structure and the derivatives dependence.
A second post, from @Ashishkafunda, describes itself as an NSE mainboard IPO analysis sourced from the RHP and lists an IPO date of the 17th. It does not add figures beyond that.
A third post in the same pull, from @RealShreekaram, is about an Indore-based flour processor planning a capacity expansion and going public. It has nothing to do with NSE and should not be read as part of this story.
That is the full extent of the same-topic discussion available here. There is no meaningful disagreement between the posts on the facts of the valuation cut, and no post offers a figure that contradicts the others. The engagement counts on these posts are small and prove nothing about the claims in them.
What to Check Before You Act on Any of This
If you applied, your application status sits with your broker, not with NSE. Broker IPO sections show whether an application was received and, later, whether shares were allotted. None of the reports reviewed here state an allotment date.
If you are reading the subscription numbers to judge demand, read them from the exchange's own published data rather than from a single broker blog. The spread between 1.46x, 2.56x, over 2x and nearly 4x on the same day is wide enough that the source matters.
Treat the gray market premium as what it is: an unofficial, unregulated number. It stood at 3% on the final day, down from earlier levels, according to The Times of India and Moneycontrol.
And keep the structural point in view. Because the offer is entirely an OFS, the listing does not hand NSE new capital to deploy. What the market is pricing is the earnings power of an exchange that draws about 60% of its operating revenue from derivatives, in a segment where SEBI sets the rules on expiries, transaction charges and retail participation. That is the exposure that survives the listing.
Download the WIkiFX app for the latest financial news and updates.
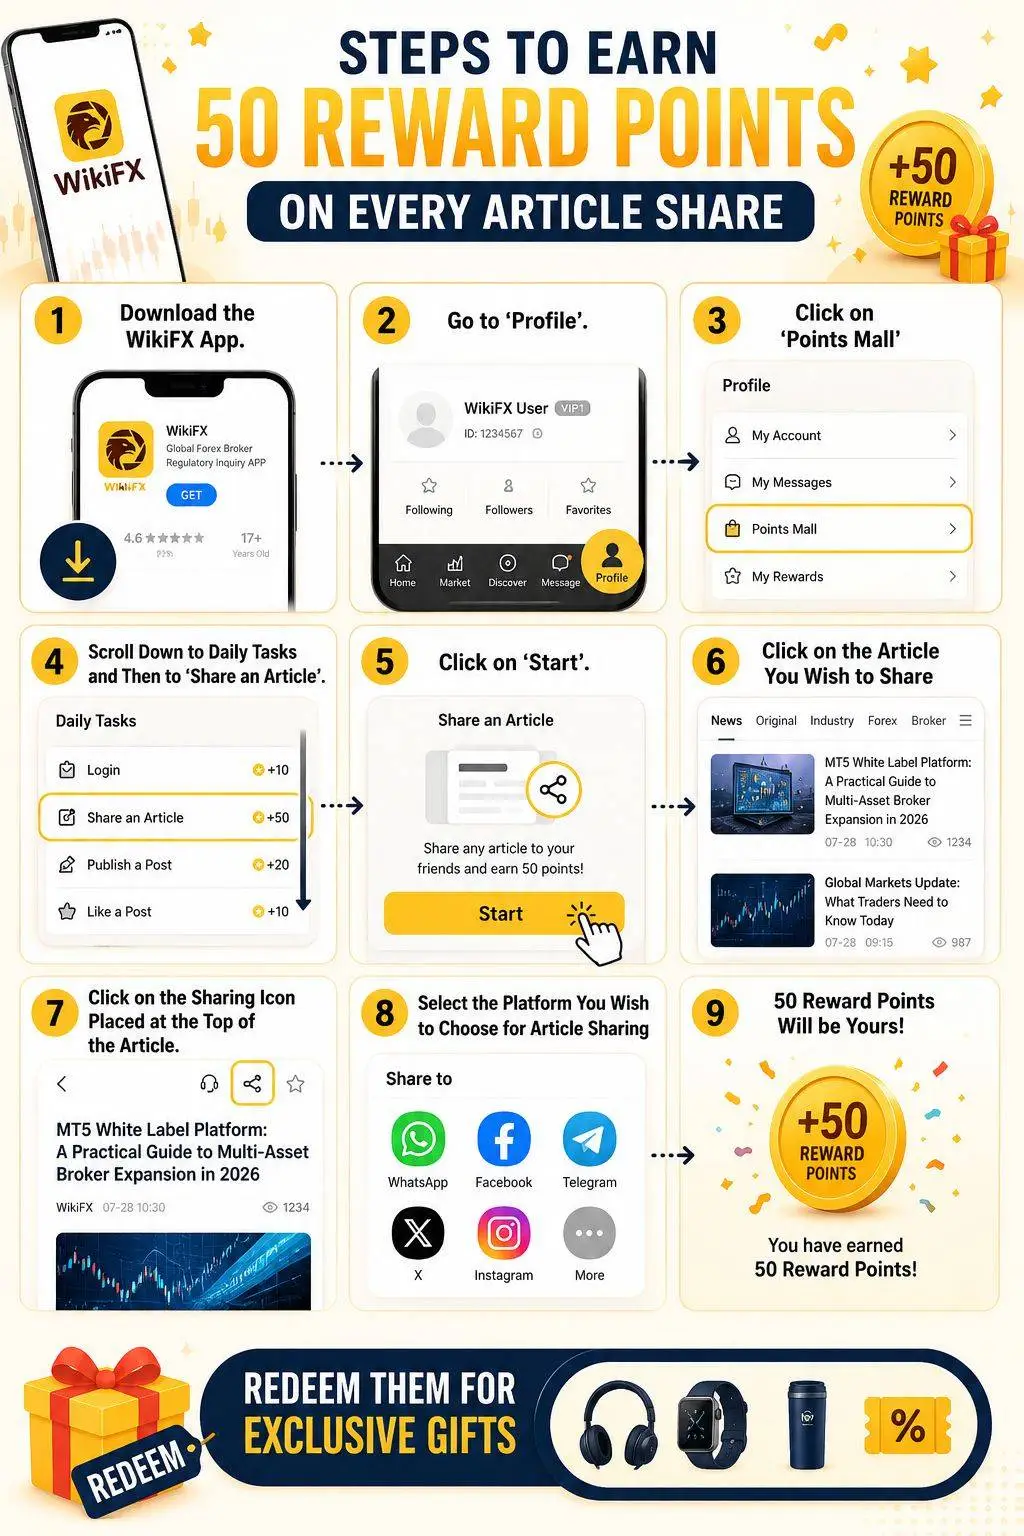
Knowledge pays at WikiFX.Every time you share a WikiFX article, you'll receive 50 Reward Points. Grow your rewards with every share and unlock exclusive gifts in the WikiFX Points Mall. Start earning today!
Read more
Uday Kotak Warns India's Gold Import Bill is Heading for $90 Billion
Gross gold imports could reach $88-90 billion in FY27, the Kotak Mahindra Bank founder told a conference in New Delhi on Friday, and he wants a committee created to work out how India pays that bill without damaging its external accounts. The same speech carried a second number. Kotak expects the current account deficit to widen to roughly $60 billion in FY27 if crude averages about $90 a barrel. Gold does most of that damage. Strip gold out, and India ran a current account surplus in FY26. He was speaking at the Conference on Financing India's Journey Towards Viksit Bharat, a gathering on capital formation. ANI carried the remarks, and a string of outlets across business media reproduced them over the weekend. "India needs to find a way to balance household demand for gold with the impact of imports on the country's external finances," Kotak said, according to Analytics Insight. He suggested the government consider setting up a committee to examine the issue. He also flagged the
NAGA Review 2026: Reported Deductions on Winning Trades and Withdrawal Issues
NAGA, a Cyprus-based brokerage firm, received numerous trading allegations from users worldwide. These users have reported unfair deductions on winning trades, fund scams, and difficulties in accessing withdrawals. These negative NAGA reviews have become frequent on broker evaluation platforms such as WikiFX. In this article, we will look closely at the trading complaints while also keeping an eye on its regulatory status.
India Just Bought a Record $15.2B of US Treasures in July — What It Means for INR and FII Flows
India bought a record $15.2 billion of US Treasures in July, lifting its total holdings to $202.6 billion from $186.4 billion in June, according to US Treasury data. The jump is the largest monthly net purchase on record for India, and it comes as China's holdings slid to an 18-year low. The figure was flagged by market commentator @Equities_Fraise on X, who noted the buying usually signals strong overseas capital inflows and RBI facilities pulling money in. The post, which has just 8 likes, points to better forex comfort and global confidence in India flows. The data itself is from the US Treasury's TIC report, released September 16.
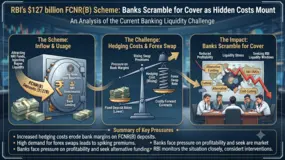
RBI's $127 billion FCNR(B) Scheme: Banks Scramble for Cover as Hidden Costs Mount
The Reserve Bank of India's special FCNR (B) deposit scheme pulled in about $127 billion from non-resident Indians — well over its initial $50 billion target. Banks are now scrambling to replace short-term borrowings with longer-term overseas funding, while critics say the true cost of the scheme could be enormous. The scheme, announced on 5 June and closed on 31 August, was designed to shore up forex reserves. But a thread by @sandeep_PT, with 67 likes, argues the RBI bears the risk of rupee depreciation on these deposits, making the hidden cost "very large." Banks offered unusually high interest rates, which will eventually fall on borrowers and shareholders. And the dollar inflows add huge rupee liquidity, forcing the RBI to absorb excess money — potentially raising government borrowing costs.
WikiFX Broker
Latest News
Interest Rate Forecast: Fed Hike Expectations Support US Dollar
WikiFXU.S. Dollar Moves Higher Despite Oils Pullback: Analysis For EUR/USD, GBP/USD, USD/CAD, USD/JPY
WikiFXNAGA Review 2026: Reported Deductions on Winning Trades and Withdrawal Issues
WikiFXFXView Broker Review: Regulated but Is It Safe for Traders?
WikiFXEconomist Warns That Tech Bubble Could Burst & Nasdaq Could Crash 72%
WikiFXTrade W Broker Review: Regulated but Is It Safe for Traders?
WikiFXAvaTrade To Close Its Office | What Does This Mean for Traders?
WikiFXUS Dollar Price Forecast: Hawkish Fed Supports DXY as EUR and GBP Struggle
WikiFXCMC Markets To Launch Prop Trading Platform on 1 OCT Amid Legal & Regulatory Concerns
WikiFXNSE Cuts Its IPO Valuation by 15% — and the Unlisted Market Is Still Pricier
WikiFXRate Calc
